- What is the NBU’s current discount rate?
- What Is the NBU’s discount rate in simple terms
- NBU Policy Rate in 2025–2026
- What the NBU’s discount rate affects
- How the policy rate affects deposits
- How the policy rate affects loans
- Why the NBU Is Changing the Policy Rate
- How the NBU’s policy rate has changed
- What Is the NBU’s double discount rate?
- How to calculate a late payment penalty using twice the NBU discount rate
- Frequently Asked Questions
On October 29, 2026, the National Bank of Ukraine decided to raise the discount rate to 16.5% per annum. This is the latest change in the regulator’s interest rate policy, aimed at maintaining the attractiveness of hryvnia-denominated assets and curbing inflationary pressures. What is the discount rate, why does the NBU adjust it, and how does this affect deposits, loans, and the economy as a whole? We’ll explore these questions below.
What is the NBU’s current discount rate?
The NBU’s current discount rate is 16.5% per annum. The National Bank’s Board adopted this decision on October 29, 2026, raising the rate by 0.5 percentage points from the previous level of 16%. The new rate took effect on October 30.
The increase is driven by a significant rise in price pressures and a deterioration in inflation expectations. The change in monetary policy is intended to support the attractiveness of hryvnia-denominated assets and the stability of the foreign exchange market, as well as to help keep inflation under control.
What Is the NBU’s discount rate in simple terms
To understand what the NBU’s discount rate is, it’s helpful to think of it as the main benchmark for the National Bank’s interest rate policy. The regulator uses this tool to influence the cost of hryvnia-denominated funds in the financial system and to shape monetary conditions for the economy.
The discount rate determines the base cost of hryvnia funds in the National Bank’s transactions with banks: the NBU uses it to extend loans to banks and attract funds from them. It also serves as a benchmark for setting interest rates in the financial market. Through its interest rate policy, the regulator influences banks’ decisions regarding lending and attracting deposits, and thus affects savings, consumer demand, economic activity, and inflation.
An increase in the discount rate signals a tightening of the NBU’s interest rate policy and creates conditions for a rise in the cost of credit and the yield on hryvnia savings. Conversely, a rate cut may contribute to a gradual reduction in the cost of financing and a decline in deposit yields. However, this does not mean that banks will necessarily adjust their rates: each institution independently sets its interest rates, taking into account its own liquidity, the cost of funds raised, risks, and customer needs.
The National Bank’s Board makes decisions on the discount rate, taking into account current and projected inflation, inflation expectations, the situation in the foreign exchange market, the state of the economy, and the balance of risks. The impact of monetary policy on prices and economic activity unfolds gradually; therefore, when making decisions, the NBU assesses not only the current situation but also the expected dynamics of economic indicators.
The National Bank also uses other monetary policy instruments, including operations to regulate bank liquidity and reserve requirement ratios. These complement interest rate policy and help the regulator influence monetary conditions.
NBU Policy Rate in 2025–2026
The table below shows how the National Bank’s policy rate changed during 2025–2026.
| Period | Policy Rate |
|---|---|
| 01.01.2025–23.01.2025 | 13,5% |
| 24.01.2025–06.03.2025 | 14,5% |
| 07.03.2025–29.01.2026 | 15,5% |
| 30.01.2026–30.07.2026 | 15% |
| 31.07.2026–17.09.2026 | 15,5% |
| 18.09.2026–29.10.2026 | 16% |
| from 30.10.2026 | 16,5% |
What the NBU’s discount rate affects
Changes in the discount rate affect the cost of hryvnia-denominated funds for banks and are one of the factors that determine lending conditions, returns on savings, consumer demand, and inflation trends. The general logic behind this impact is outlined in the table.
| If the policy rate rises | If the policy rate is lowered |
|---|---|
| Deposit yields may gradually increase | Deposit yields may gradually decline |
| Loans may become more expensive | Loans may become cheaper |
| Consumer demand and economic activity may slow down | Consumer demand and economic activity may pick up |
| Inflationary pressures may ease | Inflationary pressures may intensify |
It is important to note that these are general trends, not an automatic consequence of every decision made by the NBU. The financial market’s reaction depends on many factors, including market participants’ expectations, bank liquidity, and the overall economic situation.
How the policy rate affects deposits
The discount rate serves as a benchmark for the deposit market, as it influences the cost of hryvnia-denominated funds in the banking system. When the NBU raises the rate, banks may adjust the interest rates on hryvnia deposits to maintain the attractiveness of savings accounts and attract customer funds. After the rate is lowered, the interest rates on new deposits may also gradually decrease.
At the same time, the interest rate on a specific deposit depends not only on the discount rate. Banks take into account their own liquidity, funding needs, the term of the deposit, the cost of other funding sources, and their own interest rate policy. Therefore, a change in the NBU’s discount rate does not necessarily mean a proportional adjustment of deposit offers.
How the policy rate affects loans
The discount rate affects the cost of funds in the banking system; therefore, raising it can create conditions for an increase in loan rates. Under such conditions, loans to individuals and businesses may become more expensive, while demand for credit may decline. Conversely, lowering the discount rate can contribute to a gradual reduction in the cost of credit and a revival of lending.
However, actual lending terms are determined by many factors: the cost of funds raised by the bank, credit risks, the term and type of loan, the borrower’s financial condition, and the bank’s interest rate policy. Therefore, a change in the NBU’s discount rate does not automatically mean a revision of rates across all loan products.
Why the NBU Is Changing the Policy Rate
When setting the policy rate, the National Bank assesses the current state of the economy and forecasts how prices, demand, and financial markets will develop. Among the key factors influencing the regulator’s decision are:
- Inflation and inflation expectations. If prices are rising faster than the NBU had forecast, or if the public and businesses expect inflation to accelerate further, the regulator may tighten monetary policy.
- The situation in the foreign exchange market. Currency supply and demand, exchange rate movements, and international reserves influence the assessment of foreign exchange risks.
- The attractiveness of hryvnia savings. Sufficient returns on hryvnia-denominated instruments help sustain demand for the national currency and curb pressure on the foreign exchange market.
- Economic activity. The pace of consumption, production, investment, and lending affects aggregate demand and inflationary pressure.
- External financing and war risks. The volume and predictability of international aid, the security situation, and related risks influence macroeconomic forecasts.
- The NBU’s macroeconomic forecast. The regulator assesses the expected trends in inflation, economic growth, the foreign exchange market, and other indicators.
Decisions regarding the policy rate depend on a combination of these factors. If inflationary pressures intensify, the NBU may raise the rate to maintain the attractiveness of hryvnia-denominated assets and curb inflation expectations. If inflationary risks subside, the regulator may ease monetary policy. When the rate remains unchanged, this may also be a deliberate decision—in particular, to assess the impact of previous changes on the economy and financial markets.
How the NBU’s policy rate has changed
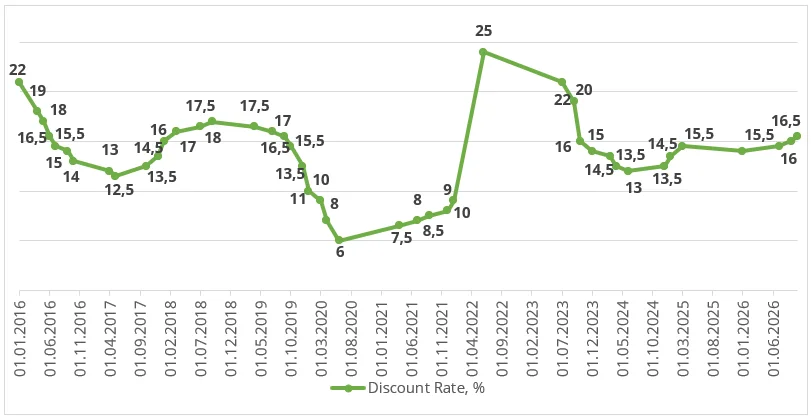
Over the past decade, the policy rate has fluctuated significantly depending on inflation trends, the state of the economy, and risks to financial stability.
In 2015, amid high inflation and currency volatility, the rate reached 30% per annum. In June 2020, however, it hit its lowest level at that time—6%. This decision was intended to support economic activity amid the pandemic. Following the start of the full-scale invasion in June 2022, the regulator raised the rate to 25% to curb inflationary pressures and support the stability of the hryvnia.
In 2023–2024, the NBU gradually lowered the rate as inflation slowed and macroeconomic conditions improved. By the fall of 2024, it stood at 13%. However, starting in December 2024, the regulator resumed raising the rate, and over the next two years, it gradually rose to 16.5% per annum.
NBU Policy Rate: Trends from 2016 to 2026
Source: National Bank of Ukraine
What Is the NBU’s double discount rate?
The NBU’s double discount rate is a calculated value equal to twice the current discount rate. It is not a separate rate set by the National Bank.
The double discount rate is used, in particular, as a threshold for calculating late payment penalties for the untimely fulfillment of monetary obligations in cases covered by the relevant legislation. Pursuant to Article 3 of the Law of Ukraine “On Liability for Late Performance of Monetary Obligations,” the amount of the penalty is calculated based on the amount of the overdue payment and may not exceed twice the NBU discount rate in effect during the period for which the penalty is assessed.
Thus, twice the NBU discount rate sets the statutory upper limit for late payment penalties under this Law. The specific amount of the penalty is determined based on the terms of the contract and the requirements of the law.
How to calculate a late payment penalty using twice the NBU discount rate
The following formula is used to calculate the late payment penalty:
Late Payment Penalty = Amount Owed × (Twice the NBU Discount Rate / 100) × (Number of Days Past Due / Number of Days in a Year).
For example, the overdue payment amounts to 10,000 UAH, the NBU discount rate is 16.5% per annum, and the period of delinquency is 30 days. To calculate the maximum penalty amount, we apply the double rate—33%:
10,000 UAH × (33 / 100) × (30 / 365) ≈ 271.23 UAH.
Thus, the maximum penalty amount for a 30-day delay under the given conditions is approximately 271.23 UAH.
If the discount rate changed during the period of delinquency, the calculation must be performed separately for each period during which the respective rate was in effect. You should also take into account the actual number of days in the year—365 or 366.
For your convenience, you can use the penalty calculator based on the NBU’s double discount rate.
Frequently Asked Questions
What is the NBU’s discount rate right now?
As of October 30, 2026, the NBU’s discount rate is 16.5% per annum. The National Bank’s Board decided to raise it from 16% on October 29, 2026, due to mounting price pressures and worsening inflation expectations.
What is the NBU’s discount rate in simple terms?
It is the National Bank’s key interest rate, which determines the cost of its operations with banks and serves as a benchmark for interest rates in the financial system. By adjusting this rate, the NBU influences the cost of loans, returns on savings, demand, and inflation.
Who sets the discount rate in Ukraine?
Decisions regarding the level of the discount rate are made by the Board of the National Bank of Ukraine.
How does the NBU’s discount rate affect deposits?
The discount rate is one of the benchmarks for the deposit market and influences the overall cost of hryvnia-denominated funds. The actual return on deposits also depends on the deposit term, the bank’s liquidity, its funding needs, and its interest rate policy.
How often does the NBU change the discount rate?
Decisions regarding the discount rate are made in accordance with a pre-announced schedule of NBU Board meetings on monetary policy. At a regular meeting, the regulator may raise or lower the rate, or leave it unchanged.